Guides › Buying an HDB resale flat
Buying an HDB resale flat: loans, stamp duty, grants and the steps
Buying an HDB resale flat: the HFE letter, HDB and bank loan limits, CPF and cash, stamp duty, grants, the timeline to keys and the MOP you take on after.
For buyers. Rules checked against HDB, IRAS, CPF and MAS on 19 September 2026; sources at the foot.
Before you offer: the HFE letter
You need a valid HDB Flat Eligibility (HFE) letter before you take an Option to Purchase and when you submit the resale application. It is valid for 9 months, and processing takes up to a month once HDB has your documents. If you are borrowing from a bank, you also need its Letter of Offer before you exercise the OTP.
Worked example: what an offer costs a buyer
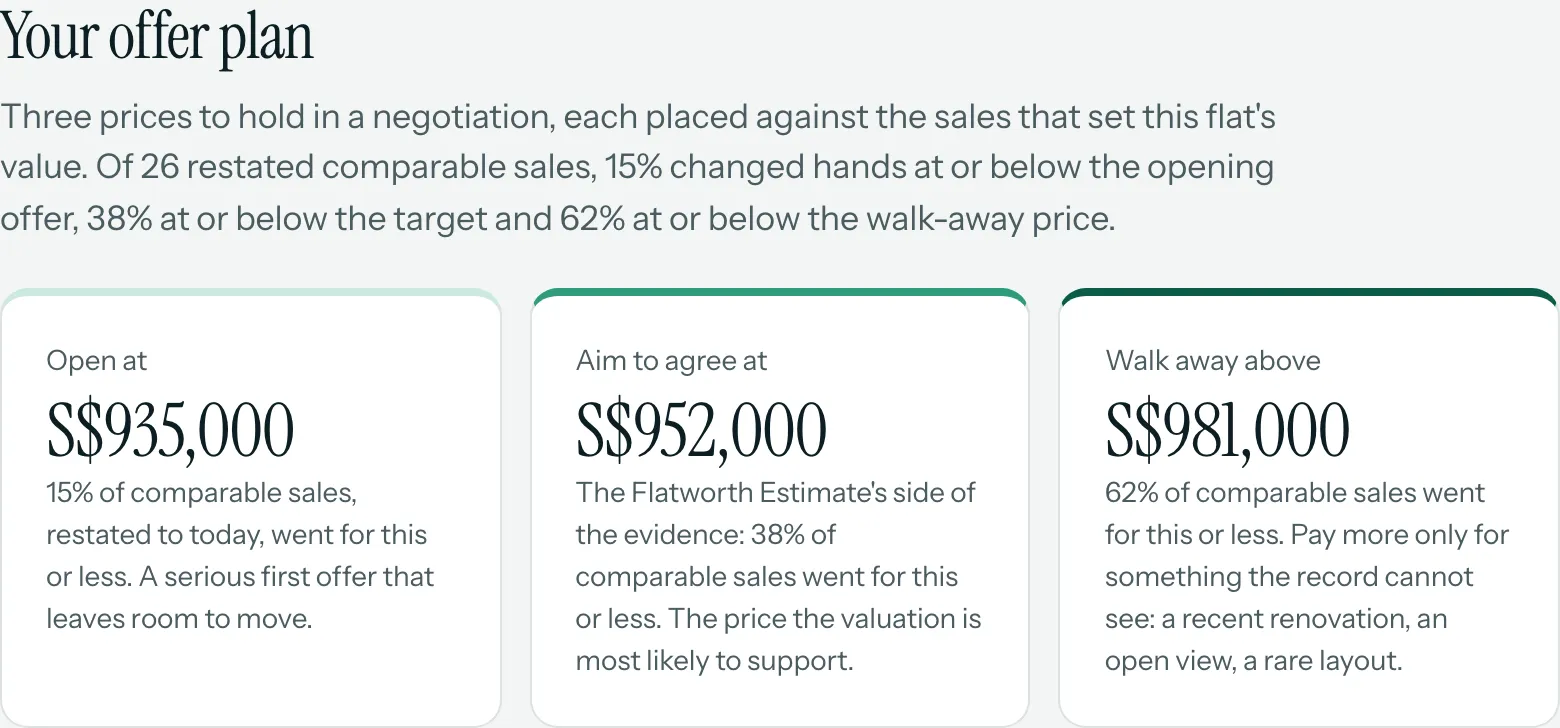
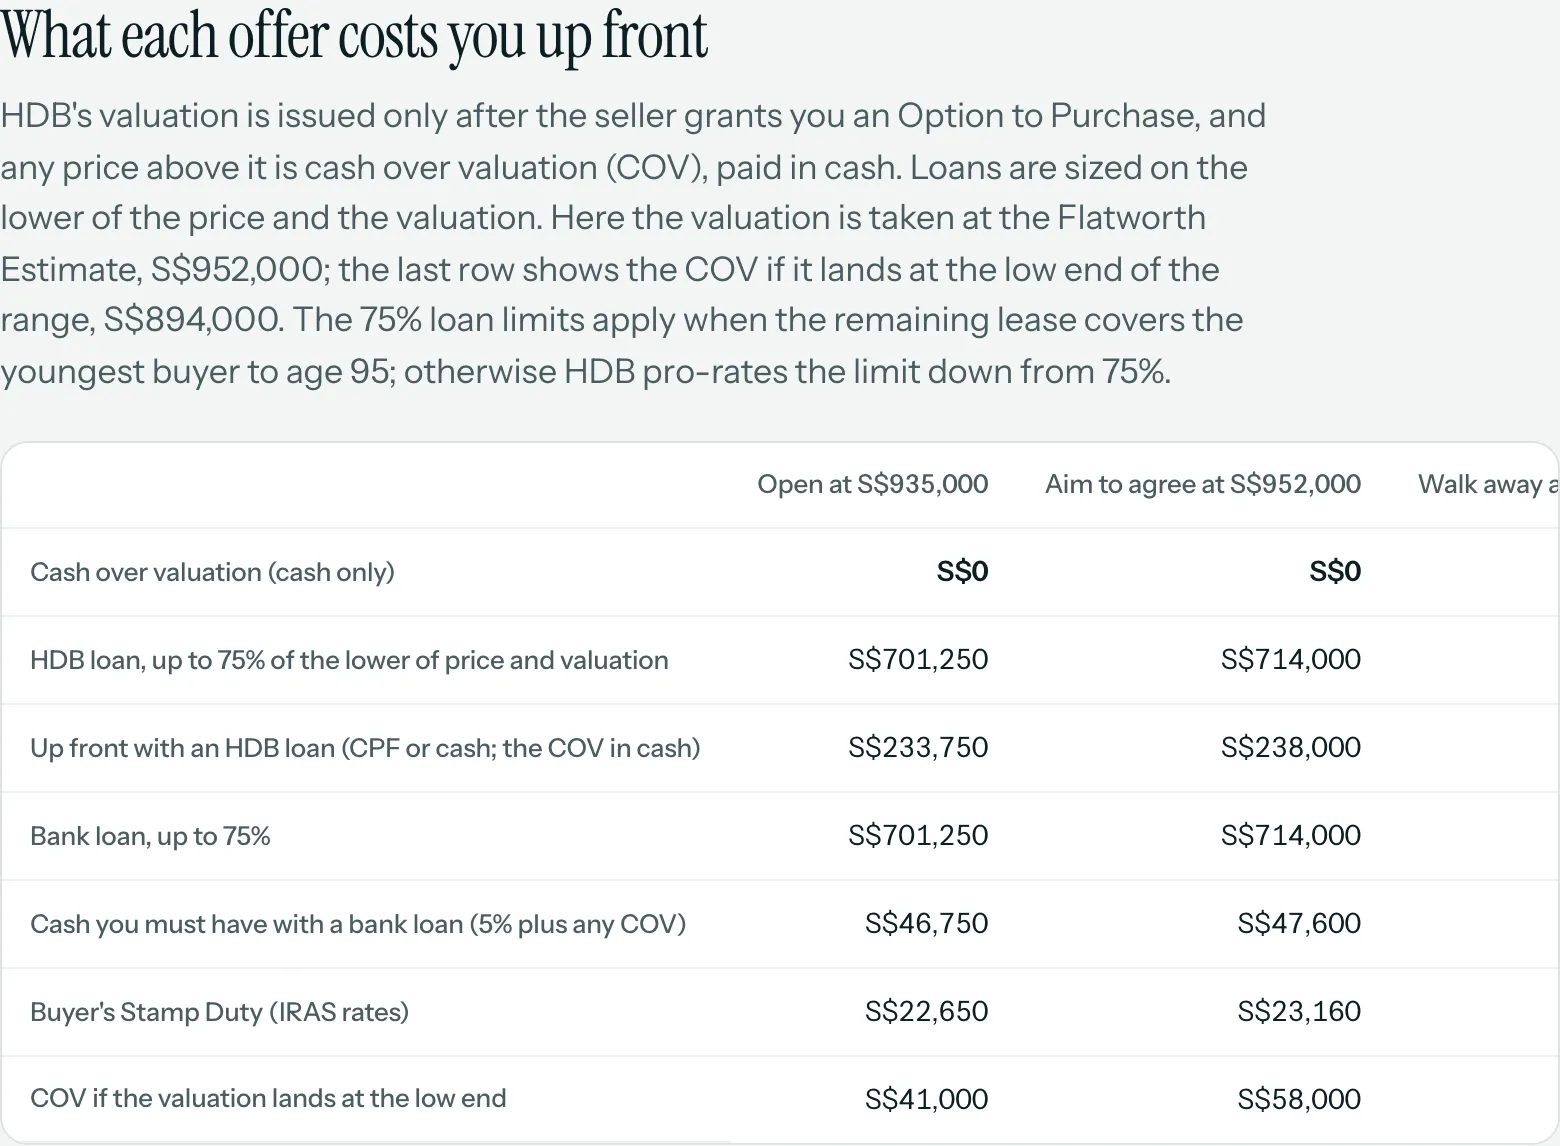
The Buyer's Report sets three prices for Blk 328 Tampines St 32 against the same 26 restated sales: open at S$935,000, aim to agree at S$952,000, walk away above S$981,000. Of those sales, 15% went for the opening offer or less, 38% for the target or less and 62% for the walk-away price or less. It then prices each offer in loan, cash, cash over valuation and stamp duty.
The arithmetic at the S$952,000 target, with an HDB loan
| HDB loan, 75% of S$952,000 | S$714,000 |
|---|---|
| Paid up front from CPF or cash | S$238,000 |
| Buyer's Stamp Duty: 1% of S$180,000, 2% of the next S$180,000, 3% of the remaining S$592,000 | S$1,800 + S$3,600 + S$17,760 = S$23,160 |
The full 75% loan and full use of CPF need the 67 years 4 months of lease left to cover the youngest buyer to age 95, which holds here for a youngest buyer of 28 or older. If HDB's valuation lands at the low end of the range, S$894,000, the same offer carries S$58,000 of cash over valuation.
Try it on your flatOpen the full sample Buyer's Report
Captured from flatworth.com on 19 September 2026 for Blk 328 Tampines St 32, an Executive flat on level 10 (147 sqm, 67 years 4 months of lease left), on sales to September 2026 and rentals to August 2026. An illustration on public records, not anyone's own flat; the live figures move as new sales register. Indications from Flatworth's own analytics on public records, not an HDB or bank valuation; Flatworth is not an HDB-appointed valuer.
How much you can borrow
| HDB loan | Bank loan | |
|---|---|---|
| Loan limit | 75% of the lower of price and value (applications from 20 August 2024) | 75% of the lower of price and value |
| If the lease does not cover the youngest buyer to 95 | Pro-rated below 75% | Bank and MAS rules apply |
| Cash you must pay | Option fee and COV; the rest can come from CPF | At least 5% of the lower of price and value, plus COV |
| Longest tenure | The shortest of 25 years, 65 minus the buyers' average age, and the remaining lease minus 20 years | Up to 30 years for HDB flats; a lower loan limit applies beyond 25 years or past age 65 |
| Repayment cap | 30% of monthly income | Mortgage Servicing Ratio 30%; all debts within 55% (TDSR) |
| Interest | 0.1 percentage point above the CPF Ordinary Account rate: 2.6% a year for July to September 2026 | The bank's rate |
What must be cash
The option fee and exercise fee (together S$2 to S$5,000; option fees cannot be paid with CPF), the S$120 Request for Value fee, the resale application fee, any cash over valuation, and with a bank loan at least 5% of the price or value. With an HDB loan you must first use your CPF Ordinary Account savings, keeping up to S$20,000 each.
Buyer's Stamp Duty
IRAS's rates for residential property, on the price or market value, whichever is higher: 1% on the first S$180,000, 2% on the next S$180,000, 3% on the next S$640,000, 4% on the next S$500,000, 5% on the next S$1,500,000 and 6% on the rest. It is due within 14 days of the date of the contract; HDB collects it for IRAS and it can be paid from CPF. Permanent Resident households buying their first HDB resale flat also pay 5% Additional Buyer's Stamp Duty; households with a Singapore Citizen buyer pay none.
| Worked example at the national 4-room median | Figure |
|---|---|
| Price | S$630,000 |
| Buyer's Stamp Duty | S$13,500 |
| Loan at 75%, if the valuation matches the price | S$472,500 |
| Paid from CPF or cash, before stamp duty | S$157,500 |
The median 4-room resale price over the twelve months to September 2026, from 10,811 sales.
Grants for resale buyers
Paid into your CPF account, they reduce what you pay. Eligibility depends on who is buying, income and past grants; your HFE letter confirms yours.
| Grant | Amount |
|---|---|
| CPF Housing Grant, first-timer family, 2- to 4-room (two citizens / citizen and PR) | S$80,000 / S$70,000 |
| CPF Housing Grant, first-timer family, 5-room or bigger (two citizens / citizen and PR) | S$50,000 / S$40,000 |
| Enhanced CPF Housing Grant, first-timer family, income up to S$9,000 | up to S$120,000 |
| Proximity Housing Grant, family: living with / near (within 4 km) parents or child | S$30,000 / S$20,000 |
| CPF Housing Grant, single, 2- to 4-room / 5-room | S$40,000 / S$25,000 |
| Enhanced CPF Housing Grant, single, income up to S$4,500 | up to S$60,000 |
| Proximity Housing Grant, single aged 35 or older: with / near | S$15,000 / S$10,000 |
| Step-Up CPF Housing Grant, eligible second-timer family | S$15,000 |
Older leases and your CPF
You can use CPF in full, up to the lower of price and value, if the remaining lease is at least 20 years and covers the youngest buyer to age 95. If it does not, CPF use is pro-rated. CPF's own example: two 25-year-olds buying a S$550,000 flat with 65 years of lease left, which runs out when they are 90, may use up to S$495,000, or 90%.
The MOP you take on
Every resale buyer must live in the flat for five years (ten for Plus and Prime flats) before selling it, renting out the whole flat, or buying private property. The MOP explained.
From HFE letter to keys: the timeline
Up to a month once HDB has all your documents; valid for 9 months. You need it before you take an OTP and when you apply.
Option fee S$1 to S$1,000, in cash. You have 21 calendar days to exercise it.
If you use CPF or a loan: by the next working day after the Option Date, S$120, outcome typically within 10 working days.
It must be valid before you exercise the OTP.
The exercise fee brings the deposit to at most S$5,000. You and the seller each submit your part within the days agreed on page 4 of the OTP and within 7 days of each other: S$80 each, S$40 for 1- and 2-room flats.
HDB accepts within 28 working days if all is in order; the documents follow about 3 weeks later.
About 8 weeks after acceptance. You pay the balance of the price, any stamp fees and your share of the property tax.
Before the loan: your CPF and the fine print
With an HDB loan, the balance in your CPF Ordinary Account goes into the purchase first; each buyer may keep up to S$20,000. HDB tests the loan at the higher of a 3.0% floor and its own rate, and caps instalments at 30% of income. HDB's rate is 0.1 percentage point above the CPF Ordinary Account rate: 2.6% a year for July to September 2026. A bank loan follows MAS rules instead: 75% of the lower of price and value with at least 5% in cash, or 55% with 10% in cash if the tenure runs past 25 years for an HDB flat or past age 65; at most 30 years; instalments within 30% of gross monthly income (MSR), and all debts within 55% (TDSR).
Stamp duty, and ABSD for PR buyers
Buyer's Stamp Duty is charged on the higher of the price and the market value, rounded down to the dollar, and HDB collects it from your CPF unless you write in to pay cash. A loan also carries mortgage stamp duty of 0.4% of the loan, at most S$500. Additional Buyer's Stamp Duty is fully remitted if any buyer is a Singapore Citizen. A PR household buying its first HDB resale flat pays ABSD at 5%, at the completion appointment; all applicants must have been PRs for at least three years, and a non-Malaysian PR household must fit the PR quota.
If you already own property
Buyers taking an HDB loan or a CPF grant must not own private residential property when they apply for the HFE letter. If you buy a non-subsidised resale flat without an HDB loan while owning private property, or you are a senior buying a short-lease flat, you must dispose of the other property within 6 months of resale completion. See what flats sell for near you on the town pages.
Work out an offer for a flatFree: the Flatworth Estimate for any block and level. The Buyer's Report gives an opening offer, target and walk-away price, with the COV, cash, CPF and stamp duty at each, S$39.
Questions people ask
How long is the HFE letter valid?
Nine months from issue. HDB takes up to a month to process it once it has all your documents.
Do PRs pay ABSD on an HDB resale flat?
A PR household pays 5% on its first HDB resale flat, at the completion appointment. If any buyer is a Singapore Citizen, ABSD is fully remitted.
Can I pay stamp duty with CPF?
Yes. HDB collects the stamp duty from your CPF by default; write to HDB if you prefer to pay cash.
How much can I borrow for an HDB resale flat?
Up to 75% of the lower of the price and HDB's valuation, from HDB (for applications from 20 August 2024) or a bank, less if the lease does not cover the youngest buyer to age 95.
How much is Buyer's Stamp Duty on an HDB flat?
IRAS's residential rates: 1% on the first S$180,000, 2% on the next S$180,000, 3% on the next S$640,000 and 4% on the next S$500,000, on the price or value, whichever is higher. On a S$600,000 flat it is S$12,600.
What must I pay in cash when buying an HDB resale flat?
The option and exercise fees, the S$120 Request for Value fee, the application fee, any cash over valuation, and with a bank loan at least 5% of the price or value.
Can I use CPF for a flat with a short lease?
Yes if the remaining lease is at least 20 years; in full only if it covers the youngest buyer to age 95, otherwise pro-rated.
Sources
The rules on this page were read on the official pages below on 19 September 2026. HDB, IRAS, CPF and MAS change them from time to time; the official page is the authority for your case.
- HDB: HFE letter
- HDB: housing loan from HDB
- HDB: housing loan from financial institutions
- MAS: MSR and TDSR
- HDB: mode of financing a resale flat
- IRAS: Buyer's Stamp Duty
- IRAS: buying HDB flats
- HDB: CPF Housing Grant (families)
- HDB: Enhanced CPF Housing Grant (families)
- HDB: Proximity Housing Grant (families)
- CPF: using CPF when the lease does not cover the youngest buyer to 95
- MAS: loan tenure and loan-to-value limits
- HDB: conditions after buying a resale flat
More guides
Selling your HDB flatRenting out your HDB flatHDB valuation and COVThe HDB MOPPrices and rents by townMOP by year
About the data
Source: HDB resale flat prices, data.gov.sg. Data as of September 2026. Source: HDB rental approvals, data.gov.sg. Data as of September 2026.
Contains information from HDB resale flat prices accessed on 16 September 2026 from data.gov.sg which is made available under the terms of the Singapore Open Data Licence version 1.0. Contains information from HDB rental approvals accessed on 16 September 2026 from data.gov.sg which is made available under the terms of the Singapore Open Data Licence version 1.0.
Flatworth is independent of HDB, URA and SLA, which do not endorse it. HDB publishes resale prices as indicative, and every figure here is an estimate, not a valuation. How the figures are made. Spotted an error? Tell us and we correct it within 48 hours.