Guides › HDB valuation and COV
HDB valuation and cash over valuation (COV), explained
How HDB's valuation works in a resale: who requests it, the S$120 fee, timing, the valuer's visit, why it sets the loan and CPF, and why COV is paid in cash.
For sellers and buyers. Rules checked against HDB, IRAS, CPF and MAS on 19 September 2026; sources at the foot.
What HDB's valuation is for
In an HDB resale, HDB may have the flat valued by a firm from its Panel of Valuers. The value is the basis for how much CPF the buyer may use and the reference for the housing loan, from HDB or a bank. It is not the price: the price is what buyer and seller agree.
Worked example: the cash over valuation on one flat
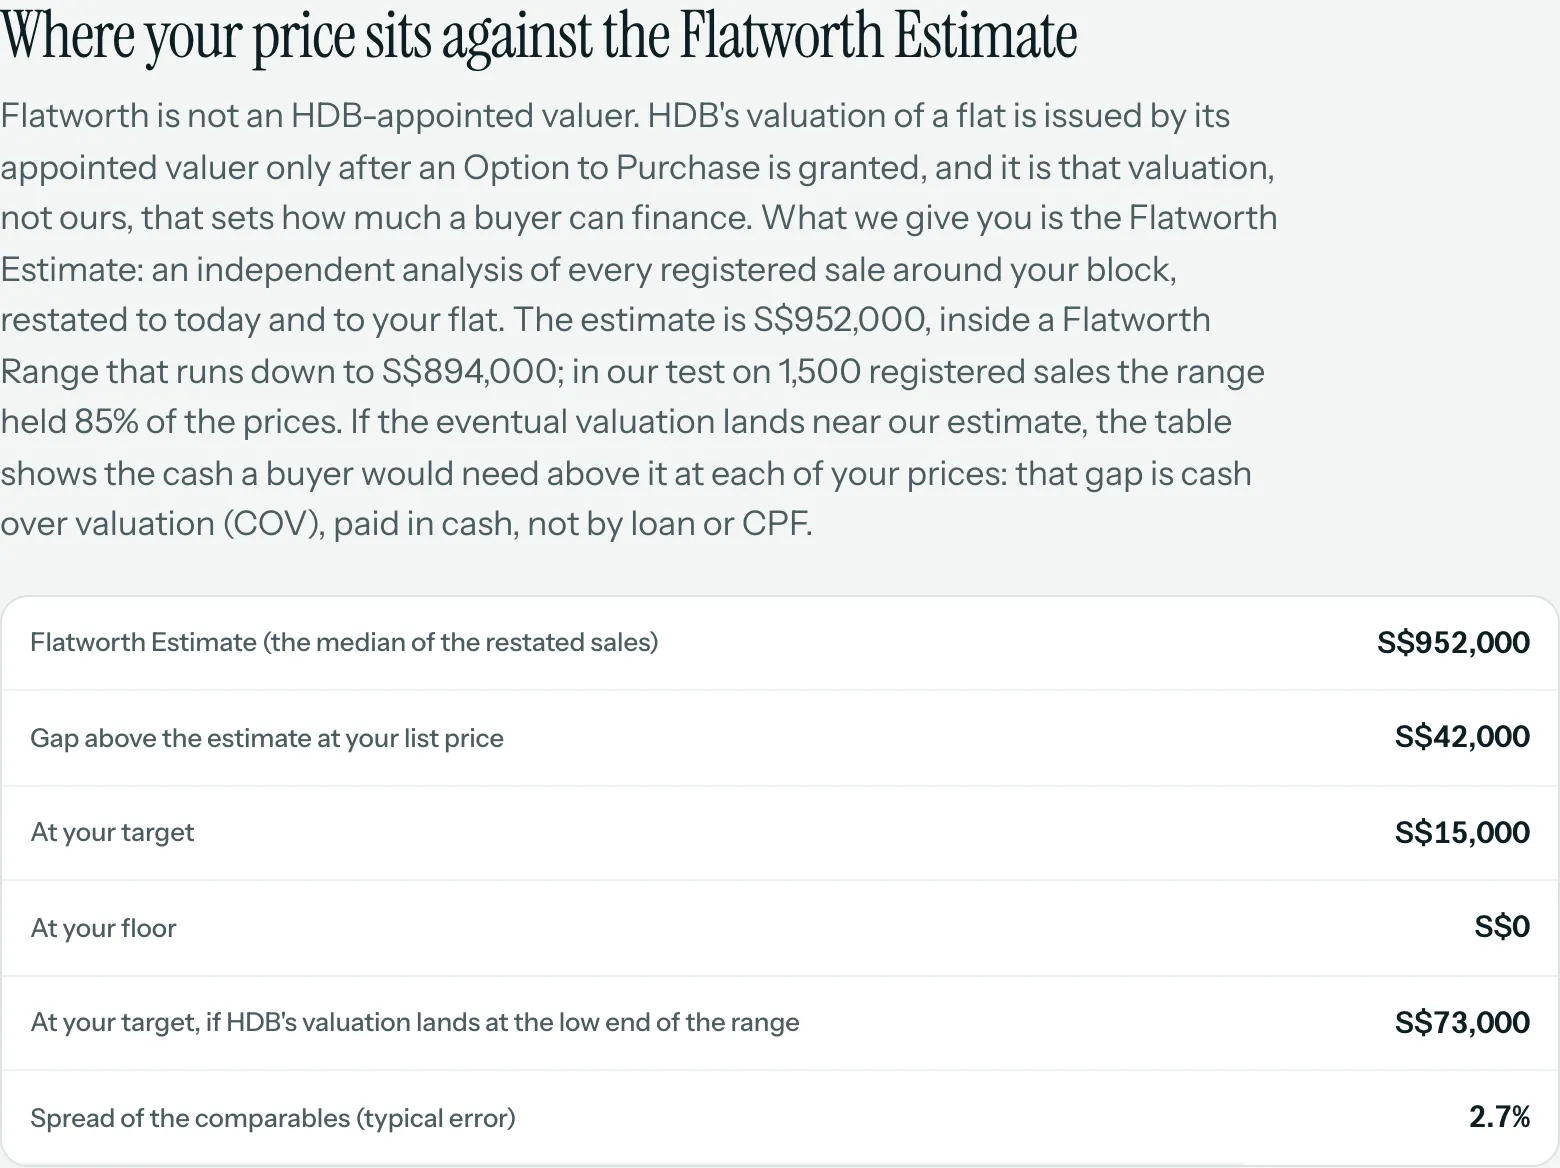
HDB's valuation arrives only after the seller grants an Option to Purchase, so both sides agree a price before they know it. For Blk 328 Tampines St 32 the Flatworth Estimate is S$952,000 and the Flatworth Range runs from S$894,000 to S$1,010,000; in Flatworth's test on 1,500 registered sales, 85% of prices fell inside the range. The report shows the cash a buyer would need at each asking price, first with HDB's valuation at the estimate, then at the low end of the range.
The arithmetic at the S$967,000 target
| Agreed price | S$967,000 |
|---|---|
| If HDB values the flat at S$952,000, the Flatworth Estimate | Cash over valuation S$15,000 |
| If HDB values it at S$894,000, the low end of the range | Cash over valuation S$73,000 |
The loan is sized on the lower of the price and HDB's valuation, so cash over valuation cannot come from a loan or CPF. The S$58,000 between those two cases is why a buyer asks for evidence before agreeing a price.
Try it on your flatOpen the full sample Flat Report
Captured from flatworth.com on 19 September 2026 for Blk 328 Tampines St 32, an Executive flat on level 10 (147 sqm, 67 years 4 months of lease left), on sales to September 2026 and rentals to August 2026. An illustration on public records, not anyone's own flat; the live figures move as new sales register. Indications from Flatworth's own analytics on public records, not an HDB or bank valuation; Flatworth is not an HDB-appointed valuer.
How it works
Only then can the buyer ask HDB for a valuation. There is no way to get HDB's valuation before an OTP.
By the next working day after the Option date, with page 1 of the OTP, paying S$120. It is needed only if the buyer uses CPF or a housing loan; a cash buyer need not submit one.
HDB decides whether a valuation is needed and assigns the valuer; the buyer may not choose one. The seller lets the valuer inspect within 3 working days of HDB's notice.
Usually within 10 working days, valid for 3 months. The buyer must have it before exercising the OTP.
Cash over valuation
COV is the difference between the agreed price and HDB's valuation. It must be paid in cash; it cannot come from a loan or CPF. Loans are sized on the lower of the price and the valuation: an HDB or bank loan of up to 75% of that lower figure.
| Example | Figure |
|---|---|
| Agreed price | S$650,000 |
| HDB's valuation | S$630,000 |
| Cash over valuation, cash only | S$20,000 |
| Loan limit: 75% of the lower of the two | S$472,500 |
| The rest, from CPF or cash, excluding the COV | S$157,500 |
An illustration of the rule, not a market figure.
Why the valuation usually sits at or below the price
The valuer prices by comparison with recent registered sales of similar flats, and registrations lag the market; and a buyer may pay for things a valuer does not credit, such as a new renovation or a rare layout. So a negotiated price tends to sit at or above the valuation. What a seller and buyer can do is know the evidence first. The Flatworth Estimate is our own estimate built the same way, from the registered sales in your block and within 500 metres; it is not HDB's valuation.
If the buyer pays fully in cash
A Request for Value is needed only when the buyer uses CPF or a housing loan. A buyer paying entirely in cash need not submit one. HDB still has sole discretion to decide whether a valuation is required.
The seller's part: the valuer's visit
HDB assigns the valuer from its Panel of Valuers; the buyer may not name one. Once HDB notifies you, you must let the valuer inspect the flat within three working days. The buyer files the Request for Value by the next working day after the Option Date, with page 1 of the OTP. The outcome is typically ready within 10 working days, stays valid for three months, and the buyer must wait for it before exercising the OTP. With a 21-day option period, a late request or a delayed inspection eats into the time left.
What the valuation decides for the buyer
The value is the basis for how much CPF the buyer may use and the reference for the housing loan, from HDB or a bank. Both lend up to 75% of the lower of the price and the value, and CPF use is capped at the lower of the two when the lease covers the youngest buyer to age 95. So a valuation below the price shrinks the loan and the CPF the buyer can use, and every dollar of the gap is paid in cash. Buying an HDB resale flat works through the loan and the cash.
How the Flatworth Estimate differs from HDB's valuation
HDB's valuation comes from a valuer on HDB's panel, for one flat, after the OTP is granted, and it is the figure that sets the loan and CPF. The Flatworth Estimate is independent analysis you can have before any of that: every registered sale of a comparable flat within 500 metres over the last 12 months, each restated to today and to your storey, size and remaining lease. The Flatworth Range around it held 85% of registered prices in a test on 1,500 sales. Use it to set an asking price or an offer that a valuation is likely to support; Flatworth is not an HDB-appointed valuer. How the figures are made.
See the evidence for a flatFree for any block and level. The Flat Report (sellers) and the Buyer's Report state the COV at each price, S$39 each.
Questions people ask
Does a cash buyer need an HDB valuation?
No Request for Value is needed when the buyer pays entirely in cash; HDB decides whether a valuation is required.
Can the buyer choose the valuer?
No. HDB assigns a firm from its Panel of Valuers, and the seller must allow the inspection within three working days.
How long is an HDB valuation valid?
Three months from when the outcome is made available.
What is COV in HDB?
Cash over valuation: the amount by which the agreed price exceeds HDB's valuation. It is paid in cash, not from a loan or CPF.
Can I get an HDB valuation before the Option to Purchase?
No. The buyer can request HDB's valuation only after the seller grants an Option to Purchase, by the next working day after the Option date.
How much does an HDB valuation cost and how long does it take?
The Request for Value costs S$120, including GST. The outcome is usually ready within 10 working days and is valid for 3 months.
Does the loan depend on the valuation?
Yes. HDB and bank loans for a resale flat are up to 75% of the lower of the price and the valuation, and CPF use is capped by the value too.
Sources
The rules on this page were read on the official pages below on 19 September 2026. HDB, IRAS, CPF and MAS change them from time to time; the official page is the authority for your case.
More guides
Selling your HDB flatRenting out your HDB flatBuying an HDB resale flatThe HDB MOPPrices and rents by townMOP by year
About the data
Source: HDB resale flat prices, data.gov.sg. Data as of September 2026. Source: HDB rental approvals, data.gov.sg. Data as of September 2026.
Contains information from HDB resale flat prices accessed on 16 September 2026 from data.gov.sg which is made available under the terms of the Singapore Open Data Licence version 1.0. Contains information from HDB rental approvals accessed on 16 September 2026 from data.gov.sg which is made available under the terms of the Singapore Open Data Licence version 1.0.
Flatworth is independent of HDB, URA and SLA, which do not endorse it. HDB publishes resale prices as indicative, and every figure here is an estimate, not a valuation. How the figures are made. Spotted an error? Tell us and we correct it within 48 hours.